Good news! Some Medicare Advantage and Part D plans in 2021 will provide supplemental benefits for insulin, including during the coverage gap (or Donut hole) phase.
A new program in 2021 called, the Part D Senior Savings Model will weigh the effects of offering people who are enrolled in Medicare more choices of insurance plans that would lower your out-of-pocket costs of insulin to $35 for a one-month supply – and these costs will stay at $35, even when you hit the Donut hole!
High insulin costs, in the past, have been a huge burden on many of my clients, being detrimental to their health and their finances.
During Medicare’s Open Enrollment this year, if you are a diabetic, you should review which plans in Maine will participate in this new program and what that may mean to the cost of your insulin and other medications.
Who is Participating?
In 2021, there will be 1,635 prescription drug plans participating in the Part D Senior Savings Model, including both Medicare Advantage Plans and stand-alone Part D Prescription Drug Plans.
For a full list of the drugs effected, click here.
To see all the plans that are participating, click here.
To talk to a local expert about this program, click here.
The new Part D Senior Savings Model was created in response to President Trump’s plan to lower the cost of insulin. For carriers with products participating in this model, a one-month supply of insulin would not cost any more than $35.
The model also intends to decrease Medicare expenses by offering a variety of supplemental benefits to cover costs such as copays and initial coverage.
The Part D Senior Savings Model’s goal is to provide beneficiaries with higher quality care and will benefit those who have either a Part D Prescription Drug plan or a Medicare Advantage Plan.
When Will These Changes Take Place?
Beginning with the Annual Enrollment Period for the 2021 plan year, which runs from October 15th to December 7th, participating insurance companies will offer Mainers on Medicare beneficiaries these supplemental benefits for insulin. The drug companies will pay the 70 percent discount for your insulin, if it is included in the program.
Under the new program, Medicare plans in Maine will offer Mainers more choices that will allow them access to more types of insulin. With the maximum copay being $35, the model projects members saving an average of over 66 percent in annual out-of-pocket costs on insulin.
Additional information on the 2021 Part D Senior Saving Model, including fact sheets and press releases, can be found linked at the bottom of the CMS report.
Would you like my help?
If you would like to talk about this program or schedule a meeting, you can reach me at 207-370-0143 or use my simple form on the CONTACT ME page of this site to send an email message.
The best part about working with me is that it w not cost you anything to discuss your options or to review the plans that are available. I am paid by the insurance companies in the form of a commission if you enroll in a plan, just like your car insurance agent.
You will not pay any more than anyone else and you are under no obligation whatsoever to enroll in any plans if you meet with me. My goal is to help you and I have found great joy in being able to offer my services to people who need my help.
If you are diabetic and using insulin, you may be able to save a lot of money.
Call me today and I will be happy to explain all your options and help you compare plans so you can choose the coverage you need for a price you can afford.
Schedule a phone call or meeting today.
I can answer all your questions over the phone or we can talk face-to-face and I can help you with everything you need to know. I have all the forms and applications you need and I can also help you complete them.
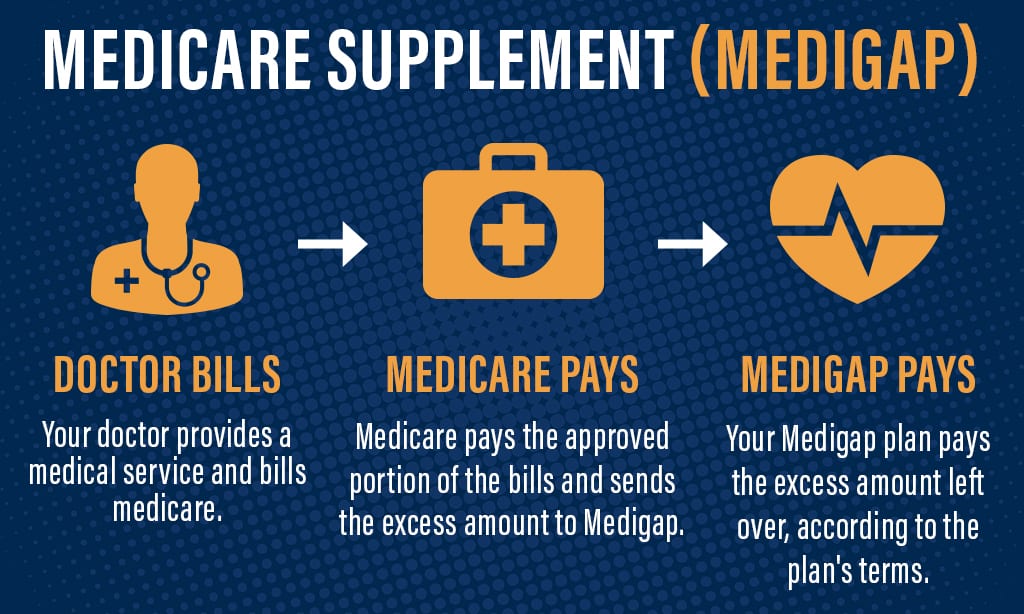
Medicare Advantage plans are very popular in Maine, but since there is no one-size-fits-all plan, Medicare Supplements (Medigap) may still be the best option for you.
Supplements work in combination with Original Medicare (Parts A & B) to fill in the gaps of the traditional Medicare program, hence the name “Medi-gap”.
Generally Medicare covers 80% of your medical cost and the Medigap plan pays most or all of the balance of copayments, coinsurance and deductibles.
Medigap plans in Maine and New Hampshire are standardized, meaning every insurance company offers identical plans, with monthly premium costs and underwriting guidelines being the primary differences between them.
In Maine and New Hampshire plans are labeled with letters A, B, D, G, K, L, M, & N. In recent years, insurance companies have added extra benefits like discount dental and vision, and fitness programs, to try and differentiate beyond price.
Medigap plans have their own set of enrollment periods and rules which vary from state to state. I can help you know when you qualify for one of these plans and go over the different options with you. There is no cost or obligation for my help.
Would you like my help?
If you would like help understanding your costs or need help finding a plan or if just want to ask a few questions, you can call 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message.
The best part about working with me is that it will not cost you anything to talk with me to discuss your options and review the plans that are available. I am an independent insurance agent and I am paid by the insurance companies (not you) in the form of a commission when you enroll in a plan.
You will not pay anything to meet with me and you will pay the same price for your insurance that everyone pays whether they had my help or not.
“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”
Medicare Rate Increases in 2021: What You May Be Able to Expect
Medicare rate increases are typically announced in November each year, so any Medicare cost changes effective for 2021 won’t be announced until late in 2020.
In this guide, we take a look at Medicare rate increases from 2019 to 2020 to shed some light on what we might be able to expect for 2021 Medicare costs.
We also outline some 2021 Medicare cost projections based on the annual Medicare Trustees Report.
2021 Medicare Part B Cost Projections
Based on reporting from the Centers for Medicare & Medicaid Services (CMS), the projected 2021 Medicare Part B premium will be $148.50 per month.1
It’s important to note that this figure only represents an estimate of 2021 Part B premiums. Actual 2021 premiums will be determined in the fall of 2020.
The standard Part B premium in 2020 is $144.60 per month. That’s an increase of $9.10 from $135.50 in 2019.
While most people pay the standard Part B premium, you may pay more if you had a higher reported income two years prior to enrolling in Medicare Part B..
The table below shows the additional amount you will pay in 2020 — called the Income-Related Monthly Adjustment Amount, or IRMAA – based on your Modified Adjusted Gross 2019 Income.
2018 Individual tax return
2018 Joint tax return
2018 Married and separate tax return
2020 Part B premium
$87,000 or less
$174,000 or less
$87,000 or less
$144.60
More than $87,000 and up to $109,000
More than $174,000 and up to $218,000
N/A
$202.40
More than $109,000 up to $136,000
More than $218,000 up to $272,000
N/A
$289.20
More than $136,000 up to $163,000
More than $272,000 up to $326,000
N/A
$376.00
More than $163,000 up to $500,000
More than $326,000 up to $750,000
More than $87,000 up to $413,000
$462.70
More $500,000
More than $750,000
More than $413,000
$491.60
Medigap plans can help cover your 2021 Medicare costs.
Call 207-370-0143 to speak with a LOCAL licensed insurance agent.
Will My Medicare Supplement Insurance Premiums Go Up?
Medicare Supplement Insurance, or Medigap, provides coverage for certain Medicare Part A and Part B out-of-pocket expenses like deductibles, coinsurance and copayments.
The lowest cost Medigap plan premium in Maine currently is $198.60 per month.2
This cost figure is weighted, which means that some 2020 Medigap plan premiums in some areas may be higher.
Each type of Medigap plan offers a different combination of standardized benefits. Plans with fewer benefits may offer lower premiums.
Other factors such as age, gender, smoking status, health and where you live can also affect Medigap plan rates.
Medigap premiums can increase over time due to inflation and other factors, so you can typically expect Medigap plan premiums to be higher in 2021 than they are currently in 2020.
Compare 2020 Medicare Supplement Insurance Plan Costs
A licensed insurance agent can help you find Medigap plans that are available where you live. You can find out the types of benefits each available plan may offer, the insurance companies that sell them and the premium costs you can expect to pay.
You can request an online plan comparison for free, with no obligation to enroll.
A local Medicare Advisor will not only dig into the details for a plan best suited for you, but assist with any service related needs you encounter after your plan becomes effective. If priorities or prescriptions change from year to year, we will conduct policy reviews to determine whether another plan is worth considering.
There is no substitute for a qualified, local professional to navigate Medicare insurance with. Check out our map to find one of our 32 local agents endorsed by Plan Advisors.
Would you like my help?
If you would like help understanding your costs or need help finding a plan or if just want to ask a few questions, you can 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message.
The best part about working with me is that it will not cost you anything to talk with me to discuss your options and review the plans that are available. I am an independent insurance agent and I am paid by the insurance companies (not you) in the form of a commission when you enroll in a plan.
You will not pay anything to meet with me and you will pay the same price for your insurance that everyone pays whether they had my help or not.
“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”
1 Medicare: Part B Premiums. (Updated April 4, 2019). EveryCRSReport.com. Retrieved from www.everycrsreport.com/reports/R40082.html.
2 TZ Insurance Solutions LLC internal sales data, 2019. This data is based on the Medicare Supplement Insurance policies TZ Insurance Solutions LLC has sold. It is not a comprehensive national average of all available Medicare Supplement Insurance plan premiums.
Not happy with your current Medicare Insurance Plan? Or just curious if there is a better plan?
Like the song says… “You better shop around!”
This is very good advice!
Whether it is groceries, heating oil, or anything else, everybody wants to get the best value for their money. And today’s options for health insurance can be pretty darn costly. That’s why it’s a good idea to shop around for the right Medicare Advantage or Prescription Drug Plan.
Cost is not the only thing to consider when comparing plans.
There are dozens of Medicare Supplemental plans available in Maine this year, all with different costs.
Keep the following things in mind when you compare plans to make sure you get the best plan!
What are the monthly premiums and deductible costs?
What will you pay for the benefits and services you’re likely to use?
Is there a limit on what you will have to pay out-of-pocket for the year?
Will you have to change pharmacies if you change plans?
What benefits are most important to you? Such as Dental, Vision, Chiropractic
Comparing costs of prescription drug coverage is another part of the cost puzzle.
Do you know how much your prescriptions will cost?
Does the plan cover the drugs you take?
What pharmacies will give you the best price?
Will the Part D coverage gap (“donut hole”) effect you? If so, when?
Only you can determine what mix of benefits and costs will work best with your needs and budget, but I can help.
I can help make it easy to compare plans so you can pick one that best meets your needs.
I can explain everything you need to know and after you’ve narrowed your choices to a few really good plans, together we will review those plans to get more details about their benefits and services.
I work with all the insurance companies and plans available and I have helped hundreds of people with this decision. I understand these plans and how they work and I can help you understand them too.
And the best part is – you pay nothing for my help!
That’s right. I help you review your plan options and answer all your questions and it won’t cost you a cent!
Why?
This is what agents do. Just like with your car insurance or home owners insurance, as your agent I work for you and I get paid by the insurance companies to help you. And not just now but throughout the year.
I am trained by each insurance company on how their plans work and what they offer plus I have clients who use these plans which gives me real experience helping them year after year. So, I know which plans are the most popular and why.
Another great thing about having someone on your side is that I am available throughout the year if you have any questions or need help! So, if you have a problem with the insurance company or if you don’t understand something you get in the mail, I will be here to help with that too!
No one plan is perfect for everyone. Each plan is different, just like each person is different. I will help you understand the differences so you can the right choice with confidence!
Would you like my help?
If you would like to talk to me or schedule a meeting at your home or a nearby meeting place, you can reach me by calling 207-370-0143 or use my simple form on the CONTACT ME page of this site to send an email message.
Again, the best part about working with me is that it will not cost you anything to meet with me to discuss your options or to review the plans that are available. I am paid by the insurance companies in the form of a commission if you enroll in a plan. You will not pay any more than anyone else and you are under no obligation whatsoever to enroll in any plans if you meet with me.
“My goal is to help you and I have found great joy in being able to offer my services to people who need my help.”
Dual Eligible Special Needs Plans (DSNP) are health plans for people who have both Medicare and Medicaid (AKA MaineCare).
What’s the difference between Medicare and MaineCare?
If you’re not sure, we can help.
Medicare provides health benefits for people over age 65, as well as people younger than 65 who qualify due to a disability. Medicare is a federal program. Medicaid, on the other hand, is managed at the state level. Medicaid provides health benefits for people with lower incomes, but the rules to qualify vary from state to state.
Can you have both Medicare and MaineCare at the same time?
Yes, some people qualify for BOTH Medicare and MaineCare. These individuals are often called “dual eligible.” This is where dual special needs plans — or “dual” plans — come in.
Dual plans work together with MaineCare and Medicare. Dual health plans cover doctor visits, hospital stays and prescription drugs and often they will include extra benefits like Dental, Vision, transportation and over-the-counter items such as aspirin, toothpaste, band-aids, and more!
Medicare/MaineCare Dual plans offer these extra benefits and features at no extra cost to you
Dual plans go beyond either MaineCare or Original Medicare alone. You will have all the Medicare and MaineCare benefits you have now plus you will have additional benefits with the dual plan you choose. And best of all, with your dual plan, you get these many extra benefits and features than at no extra cost!
These extra benefits may include:
Dental coverage of up to $3,000
Eye exams, plus credit for eyewear up to $400
Hearing exams, plus credit for hearing aids
Rides to health care visits and the pharmacy at no cost to you.
up to $100 in credits EACH MONTH to buy health-related products over the counter
and many other benefits like food cards or pet food if you have a service animal.
Want to get these extra benefits?
The best new of all is that if you qualify for these plans, you do not have to wait for Open Enrollment in the fall. You can sign sign up for a plan today!
Need more information? I can help.
If you would like to ask a question or get more information about these plans, you can call me directly at 207-370-0143 or use the simple form below to send an email message.
The best part about working with me is that it will not cost you anything to meet with me to discuss your options or to review the plans that are available. I am paid by the insurance companies in the form of a commission if you enroll in a plan. And I’m always available during the year to help with questions on how to use the plan or to offer assistance if you have any trouble!
“My goal is to help you and I have found great joy in being able to offer my services to people who need my help.”
Here is how to read and use this helpful drug benefit summary.
You get a lot of mail from Medicare & your insurance. One document to watch for is your monthly Medicare prescription drug plan “Explanation of Benefits” (EOB).
Think of your EOB as a helpful tool for managing your Part D prescription drug claims and costs.
It’s important to review your Part D Explanation of Benefits!
This document provides a summary of the prescriptions you’ve filled in the previous month and information about your drug coverage, such as:
Whether you’ve met your deductible (if you have one) and, if not, how much more you need to spend before your plan begins to pay its share.
What you have paid “out-of-pocket” to date for your prescriptions.
Which Part D coverage stage you are in
How to Read Your EOB
The first page contains a list of the six sections of information it provides. Let’s take a look at the first three sections in detail.
SECTION 1: Your prescriptions in the last month
Chart 1 shows a list of your prescriptions filled by date in the past month and which pharmacy you used. Be sure to check the accuracy of this list.
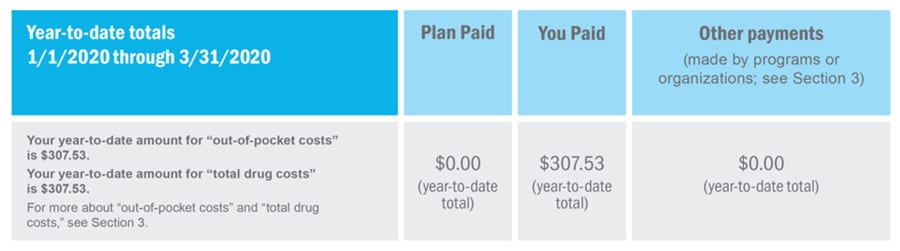
The chart displays three columns that show the amount the plan paid, what you paid, and any other payments from an organization or a program like a State Pharmaceutical Assistance Program (SPAP).
Near the bottom of the chart, you’ll see the monthly totals paid for your prescriptions. This total will include what was paid by the plan, by you, and by other programs on your behalf, if any.
The information will be identified as “total drug costs”. The section will also provide your monthly out-of-pocket costs. At the bottom, you can view the year-to-date total for what you’ve spent out of pocket on prescriptions. Finally, a total of the three columns indicates what you, your plan, and other organizations, if any, have spent since January 1. This information will be identified as “year-to-date total drug costs”.
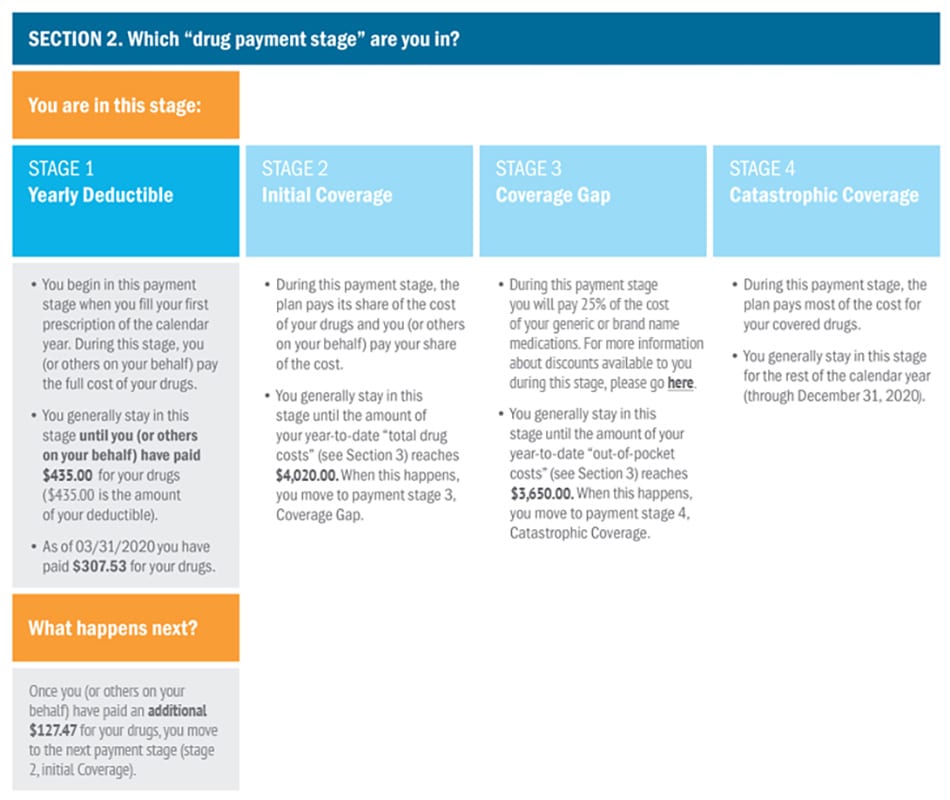
SECTION 2: The Part D drug payment stages
In this view, the stage you’re in is identified by a shaded outline—for more information on the stages of coverage, please go here. Here you will see a description of the dollar amount you and/or your plan need to reach before moving to the next stage of coverage. This information will be identified as “total drug costs”. It will also show your current year-to-date “total drug costs,” which indicate how close you are to moving to the next stage of coverage.
The bottom section of the shaded box “What happens next?” gives you the additional amount that you, your plan and others on your behalf (if any) need to spend in “total drug costs” to move to the next payment stage.
This is especially important if you are in the Initial Coverage stage, because you will see how close you are to entering the Coverage Gap (aka Donut Hole), when you will pay more for your prescriptions.
Before you get too close to the gap, you might want to review your medications with your insurance agent or broker to see what you will pay Ask if there are ways to delay entering this stage, such as by switching to a generic medication or using a coupon or Patient Assistance Program.
SECTION 3:“Out-of-pocket” and “total drug costs” amounts and definitions This section provides your monthly and yearly“out-of-pocket costs” and “total drug costs” along with definitions of what these costs include or do not include.
Additional Information
The last three sections provide information on various topics.
Section four may include changes to your Drug List that affect drugs you take, such as a change to the coverage or cost of a drug.
Section five tells you what to do if you find a mistake in the EOB or have questions.
Additionally, you can find information about protecting yourself from fraud and how to contact the plan or Medicare with your concerns. Section six discusses the plan’s Evidence of Coverage, the benefits booklet that explains the plan and the rules you need to follow to obtain drug coverage. Certain chapters and topics are highlighted that will provide you with instructions if you have issues related to your drug coverage or difficulty paying for your drugs
Want to know more? I can help!
If you would like help finding answers to your questions, you can call me directly at 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message. I am always happy to help!
The best part about working with me is that it costs you nothing! I am paid by the insurance companies in the form of a commission when I enroll someone in a plan. This is the same way it works when you buy car insurance or your home owners insurance. You do not pay anything to the agent and you will pay the same price for your insurance that everyone pays whether they had my help or not.
“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”
A Health Savings Account (HSA) is a type of savings account like an IRA that lets you set aside money on a pre-tax basis to pay for qualified medical expenses.
By using untaxed dollars in a HSA to pay for deductibles, copayments, coinsurance, and some other expenses, you may be able to lower your overall health care costs. HSA funds generally may not be used to pay premiums.
While you can use the funds in an HSA at any time to pay for qualified medical expenses, you may contribute to an HSA only if you have a High Deductible Health Plan (HDHP) – generally a health insurance plan that only covers preventive services before the deductible.
For 2020, the minimum deductible for an HDHP is $1,400 for an individual and $2,800 for a family. When you view plans in the Marketplace, you can see if they’re “HSA-eligible.”
For 2020, if you have an HDHP, you can contribute up to $3,550 for self-only coverage and up to $7,100 for family coverage into an HSA. HSA funds roll over year to year if you don’t spend them. An HSA may earn interest or other earnings, which are not taxable.
Some health insurance companies offer HSAs for their HDHPs. Check with your company. You can also open an HSA through some banks and other financial institutions.
HSA funds are not taxed when they are withdrawn from the HSA as long as they are used to pay for qualified medical expenses.
Your current employer may oversee your HSA or you may have an individual HSA that is overseen by your bank, credit union or insurance company.
HSA & Medicare
If you have an HSA and you will soon be eligible for Medicare, it is important to plan ahead and understand how enrolling in Medicare will affect your HSA.
IMPORTANT: When you enroll in Medicare Part A you can no longer contribute to your HSA.
The month you enroll in Medicare Part A (typically the month of your 65th birthday), the account overseer switches the contributing balance to your HSA to zero dollars per month.
By law, people with Medicare are not allowed to put money into an HSA. This is because you must have a high deductible health plan if you are putting money into an HSA and since Medicare will cover costs before your deductible, you no longer meet this criteria.
The Good News!
The good news is you may withdraw money from your HSA after you enroll in Medicare to help pay for medical expenses (deductibles, Part B premiums, copays or coinsurances). If you use the account for qualified medical expenses, it will continue to be tax-free.
Triple Tax Advantage of HSAs
Your account contributions are pre-tax or tax-deductible.
All earnings, interest, and, yes, investment returns are tax-free.
Any withdrawals for qualified medical expenses are tax-free. Plus, once you reach age 65, all non-medical withdrawals are taxed at your current tax rate, just like a traditional IRA. (If you withdraw money for non-medical expenses before you’re 65, then there’s a 20% penalty.)
Should you delay enrolling Medicare?
Whether you should delay enrollment in Medicare so you can continue contributing to your HSA depends on your circumstances. If you work for a small employer (fewer than 20 employees) or if you are self-employed you willneed to enroll in Medicare when you first qualify even though you will lose the tax advantages of your HSA.
Health care coverage from small employers or individual plans pay secondary to Medicare. This means that if you fail to enroll in Medicare when you are first eligible, you may have little or no health coverage.
Health care coverage from large (20 or more employees) employers pays primary before Medicare so you may not need to have Medicare in order to pay your health expenses. This means that if you are currently working for a large employer and you wish to decline Medicare Part A and/or B, you can do so and enroll in Part B later when you lose your current employer coverage. [Read more about working past age 65.]
Do you live in New Hampshire?
New Hampshire has a Medicare Plan similar to your HSA called a Medicare Savings Account (MSA) Plan. This plan works differently in that instead of you setting money aside for the HSA account, Medicare deposits the money in the account – and you keep it!
Medicare Savings Account (MSA) Plans
Medicare Medical Savings Account (MSA) plans are high-deductible healthcare plan that the federal government pays to administer Medicare benefits.
Like all Medicare Advantage plans under Part C, MSA plans must provide you with the same benefits, rights, and protections as Original Medicare, but they may do so with different rules, restrictions, and costs.
Some MSAs offer additional benefits, such as dental, vision and hearing care but unlike other Medicare Advantage Plans, MSA plans include both a high deductible health plan (HDHP) and a bank account to help pay your medical costs.
MSA plans also come with a bank account where Medicare deposits funds once each year for your medical expenses, which you can use to pay for your deductible.
Your plan chooses the bank account and the amount it contributes.
Funds contributed to an MSA are not taxed, as long as they are used to pay for qualified medical expenses.
Unlike an HSA, you cannot deposit more money into the account. Once you have used the money in the account, you have to pay out of pocket until you reach your deductible.
After reaching your deductible, your MSA plan covers 100% of the cost for Medicare-covered services.
MSA plans do not have provider networks so you may see any doctor, specialist or hospital that accepts Medicare.
Medicare MSA plans are currently only available in New Hampshire but due to their popularity I am confident they will come to Maine very soon.
In my personal opinion, MSA plans are one of the most consumer-friendly products available in the whole Medicare Advantage space – if not the whole of Medicare.
[READ MORE ABOUT MSA PLANS]
Still have more Questions?
If you would like help finding answers to your questions, you can call me directly at 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message. I am always happy to help!
The best part about working with me is that it costs you nothing! I am paid by the insurance companies in the form of a commission when I enroll someone in a plan.
This is the same way it works when you buy car insurance or your home owners insurance. You do not pay anything to the agent and you will pay the same price for your insurance that everyone pays whether they had my help or not.
“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”
Mainers who cannot afford their medications should know that many public and private programs are available to provide free or low-cost prescription medicines if you qualify.
Tell your insurance agent if you can’t afford your medicines.
Your agent can help you access these programs. As an agent I have a lot of experience helping people find Medicare and individual health insurance coverage for expensive drugs.
And because I deal with this issue almost every day, I know what programs may be best suited to help. Your insurance agent or broker that helps you review your coverage every year also should have a good idea how to help.
I put together the following list of resources that I use every day to help my clients. I hope you find it helpful. If you want my help or just want to ask a question fill out the form at the bottom of this page to send me an e-mail or call me anytime at 207-370-0143 and I will do mt best to help you!
Talk to your doctor
Your doctor’s office can help you apply to these programs themselves or refer you to one of Maine’s 15 hospital-based prescription assistance programs. Don’t put yourself at increased risk of getting sicker by skipping the medicines you need because it’s too expensive.
Whether or not you have a Medicare Supplement plan with a separate Part D prescription plan or an all-in-one type Medicare Advantage plan that includes prescription drug coverage, your cost for prescriptions can increase when you hit the donut hole.
Medicare Savings Programs (MSP, QMB, SLMB, QI)
If you have Medicare but need help with prescription drug costs, the MSP can be a huge help. Depending on what level you qualify for, you could get help paying for Part B and Part D premiums, copays, coinsurance, and deductibles. [READ MORE]
DEL PROGRAM (Low Cost Drugs for the Elderly or Disabled)
Many people who are either disabled or 62 and older who do not qualify for MaineCare, can get this help. DEL provides an 80% discount off the cost of many commonly used drugs. Some people with high medication costs may be able to get coverage of less commonly used drugs. If you are over 65 and already have Medicare, DEL does not take the place of Part D (Medicare prescription coverage). But, it may help to “wrap around” the Part D coverage in some cases. If you are eligible, it is good to apply for DEL.
Maine Rx Plus
Maine Rx Plus provides a 60% discount off the cost of many commonly used generic drugs at many pharmacies across Maine (only 15% off brand-name drugs). There may be other programs that can help pay more of your drug costs, but if not, it is good to apply for MaineRx Plus.
State prescription assistance programs like Maine Rx Plus can be helpful, but sometimes those programs don’t help enough. Community-based Prescription Assistance Programs (CPAPs) can search through their database to find other programs to help with the cost of medications. The CPAPs keep the latest information on a large number of drug company discount cards and discount programs for specific drugs. Staff can provide you with free information and help you to apply for discounts. For more information, see this flyer: Help with Prescriptions.
$4 Generics List Available at Most Pharmacies
Another way to save on prescriptions is by switching to generic. Generic medications can sometimes be less expensive than brand name drugs and may make it easier to find discounts.
Many pharmacies have started providing generic medications for only $4, regardless of your income or insurance status. Smaller, local pharmacies sometimes have generous discount programs as well. It’s a good idea to call the pharmacies nearest to you and ask about any discount programs that they offer.
Each Pharmacy will have a list of drugs they offer at $4. If your drug is not on the list call around. Each pharmacy has a different list so if you don’t find your generic drug on one list it may be on another. [READ MORE ABOUT HOW THESE $4 COPAY LISTS WORK]
Free Samples
Sometimes Health Centers, Hospitals, and Free Clinics are given free samples of certain medications that they can share with their patients. This assistance is usually not a long-term solution, but can definitely help! Whenever you are prescribed a medication, it never hurts to ask if there are free samples available.
Safely Ordering Drugs from Canada
For information about mail-ordering drugs from Canada, visit the Health Canada website to learn how to protect yourself from fraudulent companies.
Help with Private Insurance Co-pays
Even if you have health insurance through the Maine Health Insurance Marketplace, cost may still be an issue. Some people may be able to get help paying their co-pays if they meet certain income and medical guidelines. For more information visit the Patient Advocate Foundation’s Co-pay Relief website or call us at (207) 370-0143 for more details.
TRICARE
Military retirees, and some family members or former spouses age 65 and older may be eligible for two programs provided by the Department of Defense: TRICARE for Life and the TRICARE Senior Pharmacy Program. For more information and complete eligibility requirements for the TRICARE for Life and TRICARE Senior Pharmacy Program, contact Sierra Military Health Services (the Northeast Regional Contractor) toll free at 888-999-5195.
Veterans Benefits
CHAMPVA is a health care benefits program through the Department of Veterans Affairs (VA). For the spouse or widow(er) and for the children of a veteran who: is rated permanently and totally disabled due to a service-connected disability; was rated permanently and totally disabled due to a service-connected condition at the time of death; died of a service-connected disability; died on active duty and the dependents are not otherwise eligible for DoD TRICARE benefits. Under CHAMPVA, VA shares the cost of covered health care services and supplies with eligible beneficiaries.
VA and Medicare
As a Medicare-eligible Veteran, you have more options when it comes to healthcare and costs savings programs. To confirm your options call the Veterans Administration directly at 1-877-222-VETS (8387). [READ MORE ABOUT HO MEDICARE WORKS WITH VA BENEFITS]
HIV/AIDS Assistance
If you have been diagnosed with HIV and you are a resident of Maine, you could get assistance from the State of Maine to get HIV-related medications free of charge. The Aids Drug Assistance Program (ADAP) is a program of the Maine Center for Disease Control and Prevention (Maine CDC), HIV/STD Division. If you are interested in ADAP contact the Maine CDC at (207) 287-2899. You can also contact one of the HIV/AIDS organizations in the state or contact the AIDS Hotline at 1-800-851-2437.
Hospital Programs
Many hospitals in Maine provide free or reduced-cost emergency services to people at certain income levels. Some hospitals go above and beyond just the emergency services and will also provide help with medications and other services. If you have questions about free care in Maine you can call the Maine Consumer Assistance Helpline at 1-800-965-7476.
MedAccess
MedAccess works with individuals and health care providers to identify ways patients can save money on prescription medications. The free program, administered by MaineHealth, helps patients and health care providers evaluate options such as pharmaceutical companies’ patient assistance programs, low-cost generic programs, and Medicare Part D and state and local prescription programs that can help save on prescription medication costs. For more information, see the MaineHealth MedAccess Program. MedAccess is part of the MaineHealth CarePartners Program.
Drug Safety, Effectiveness, and Cost
Consumer Reports Health Best Buy Drugs offers free, trusted educational resources to help you access the safest, most effective, and most affordable prescription drugs available. This resource is a grant-funded project providing independent, evidence-based reports on prescription drugs based on research conducted at the Drug Effectiveness Review Project,
Consumer Reports Health “translates” findings into consumer-friendly reports that are available for free. These reports identify drugs that are as effective and safe as others in its class but often available at a lower cost, as well as provide information about the underlying condition. These recommended drugs are often generic drugs, but in the case that a brand-name drug is superior to a lower-cost drug in safety or efficacy, it is recommended regardless of price. The reports are freely accessible at Consumer Reports Best Buy Drugs, and also available in a printed booklet. Fill out the form below to request a free booklet get mailed to you. Remember to include your address! 😊
The Centers for Medicare & Medicaid Services (CMS) has finally announced the 2020 Medicare premiums, deductibles, and coinsurance amounts.
Medicare Part B Premium will be $144.60 per month in 2020
Medicare Part B covers doctors and specialist visits, outpatient hospital services, certain home health services, durable medical equipment, and other medical and health services not covered by Medicare Part A.
Each year the Medicare premiums, deductibles, and coinsurance rates are adjusted according to the Social Security Act.
For 2020, the Medicare Part B monthly premiums and the annual deductible are increasing. The standard monthly premium for Medicare Part B enrollees will be $144.60 for 2020, an increase of $9.10 from $135.50 in 2019. If you are paying quarterly you bill will increase to $433.80.
Medicare Part B Annual Deductible will be $198 in 2020
The annual deductible for all Medicare Part B beneficiaries is $198 in 2020, an increase of $13 from $185 in 2019.
If you have a Medigap plan that does not cover the Part B deductible then you must pay this amount first before your plan picks up any costs.
Medicare Part B Income-Related Monthly Adjustment Amounts for people with Higher Incomes
If you earn more than $87,000 and are single or more than $174,000 and are married your Part B monthly premium will be increased based on your income.
These income-related monthly adjustment amounts (IRMAA) affect roughly 10 percent of people with Medicare Part B. The 2020 Part B total premiums for high income beneficiaries are shown in the following table:
Beneficiaries who file individual tax returns with income:
Beneficiaries who filejoint tax returns with income:
Income-related monthly adjustment amount
Total monthly premium amount
Less than or equal to $87,000
Less than or equal to $174,000
$0.00
$144.60
Greater than $87,000 and less than or equal to $109,000
Greater than $174,000 and less than or equal to $218,000
$57.80
$202.40
Greater than $109,000 and less than or equal to $136,000
Greater than $218,000 and less than or equal to $272,000
$144.60
$289.20
Greater than $136,000 and less than or equal to $163,000
Greater than $272,000 and less than or equal to $326,000
$231.40
$376.00
Greater than $163,000 and less than $500,000
Greater than $326,000 and less than $750,000
$318.10
$462.70
Greater than or equal to $500,000
Greater than or equal to $750,000
$347.00
$491.60
Premiums for high-income beneficiaries who are married and lived with their spouse at any time during the taxable year, but file a separate return, are as follows:
Beneficiaries who are married and lived with their spouses at any time during the year, but who file separate tax returns from their spouses:
Income-related monthly adjustment amount
Total monthly premium amount
Less than or equal to $87,000
$0.00
$144.60
Greater than $87,000 and less than $413,000
$318.10
$462.70
Greater than or equal to $413,000
$347.00
$491.60
Medicare Part A Premiums/Deductibles
Medicare Part A covers inpatient hospital (overnight hospital stays), skilled nursing facility, and some home health care services. About 99% of Medicare beneficiaries do not have a Part A premium since they have earned the minimum 40 quarterly credits as they earned their Social Security benefit.
The Medicare Part A inpatient hospital deductible that beneficiaries will pay when admitted to the hospital will be $1,408 in 2020, an increase of $44 from $1,364 in 2019.
The Part A inpatient hospital deductible covers beneficiaries’ share of costs for the first 60 days of Medicare-covered inpatient hospital care in a benefit period. In 2020, beneficiaries must pay a coinsurance amount of $352 per day for the 61st through 90th day of a hospitalization ($341 in 2019) in a benefit period and $704 per day for lifetime reserve days ($682 in 2019).
For beneficiaries in skilled nursing facilities, the daily coinsurance for days 21 through 100 of extended care services in a benefit period will be $176.00 in 2020 ($170.50 in 2019).
Part A Deductible and Coinsurance Amounts for Calendar Years 2019 and 2020 by Type of Cost Sharing
2019
2020
Inpatient hospital deductible
$1,364
$1,408
Daily coinsurance for 61st-90th Day
$341
$352
Daily coinsurance for lifetime reserve days
$682
$704
Skilled Nursing Facility coinsurance
$170.50
$176
People age 65 and over who have earned fewer than 40 quarters and certain persons with disabilities pay a monthly premium in order to voluntarily enroll in Medicare Part A.
Individuals who had at least 30 quarters of coverage or were married to someone with at least 30 quarters of coverage may buy into Part A at a reduced monthly premium rate, which will be $252 in 2020, a $12 increase from 2019.
Certain uninsured individuals who have less than 30 quarters of coverage and certain individuals with disabilities who have exhausted other entitlement will pay the full premium, which will be $458 a month in 2020, a $21 increase from 2019.
What will you pay?
Well, that depends on what type of insurance you have. Some people have insurance plans called Medigap plans that cover 100% of your out of pocket costs so they do not pay any deductibles or copays.
Other people who have Medicare Advantage Plans may pay very little per month (in some cases $0 per month) and will only pay copays when they see a doctor or other providers.
If you would like help understanding your costs or need help finding a plan or if just want to ask a few questions, you can call me directly at 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message.
The best part about working with me is that it will not cost you anything to talk with me to discuss your options and review the plans that are available. I am an independent insurance agent and I am paid by the insurance companies (not you) in the form of a commission when you enroll in a plan.
You will not pay anything to meet with me and you will pay the same price for your insurance that everyone pays whether they had my help or not.
“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”
The Centers for Medicare and Medicaid Services (CMS) has released the 2020 costs for a standard Part D prescription drug plans.
Here are the highlights for the CMS defined Standard Benefit Plan changes from 2019 to 2020. This “Standard Benefit Plan” is the minimum allowable plan to be offered by insurance company who has a contract with Medicare to offer Part D prescription drug insurance.
Initial Deductible: will be increased by $20 to $435 in 2020.
Initial Coverage Limit (ICL): will increase from $3,820 in 2019 to $4,020 in 2020.
Out-of-Pocket Threshold: will increase from $5,100 in 2019 to $6,350 in 2020.
Coverage Gap (donut hole): begins once you reach your Medicare Part D plan’s initial coverage limit ($4,020 in 2020) and ends when you spend a total of $6,350 in 2020.
2020 Donut Hole Discount:
Part D enrollees will receive a 75% Donut Hole discount on the total cost of their brand-name drugs purchased while in the Donut Hole. The discount includes, a 70% discount paid by the brand-name drug manufacturer and a 5% discount paid by your Medicare Part D plan. The 70% paid by the drug manufacturer combined with the 25% you pay counts toward your TrOOP or Donut Hole exit point.
For example: If you reach the Donut Hole and purchase a brand-name medication with a retail cost of $400, you will pay $100 for the medication, and receive $380 credit toward meeting your 2020 total out-of-pocket spending limit.
Medicare Part D beneficiaries who reach the Donut Hole will also pay a maximum of 25% co-pay on generic drugs purchased while in the Coverage Gap (receiving a 75% discount). For example: If you reach the 2020 Donut Hole, and your generic medication has a retail cost of $40, you will pay $10. The $10 that you spend will count toward your TrOOP or Donut Hole exit point.
Minimum Cost-sharing in the Catastrophic Coverage Portion of the Benefit
You will be charged $3.60 for those generic or preferred multisource drugs with a retail price under $72 and 5% for those with a retail price greater than $72.
For brand-name drugs, You would pay $8.95 for those drugs with a retail price under $179 and 5% for those with a retail price over $179.
Maximum Co-payments below the Out-of-Pocket Threshold for certain Low Income Full Subsidy Eligible Enrollees: will increase to $3.60 for generic or preferred drug that is a multi-source drug and $8.95 for all other drugs in 2020. [Read more about these programs]
If you live in Maine or New Hampshire and would like to learn more about the new Medicare plans for 2020 or to go over the changes in your plan, you can call me at (207) 370-0143 or CLICK HERE to send me an email message.
You can also use the BOOK APPOINTMENT button below to set up a time to speak with me on the phone or in person. I can also send you information in the mail if you choose.
Have a question that needs to be answered right away? You can talk to a licensed insurance agent by calling (207) 370-0143 or toll free 866-976-9038.







 Triple Tax Advantage of HSAs