Important Questions to Ask

Before joining a Medicare Advantage Plan here are some important questions to ask.

When you are choosing between Medigap and Medicare Advantage or between Medicare Advantage Plans, here are some questions to keep in mind.

Providers, hospitals, and other facilities

  • Will I be able to keep my doctors? Are they in the plan’s network?
  • Do doctors and providers I want to see in the future take new patients who have this plan?
  • If my providers are not in-network, will the plan still cover my visits?
  • Which specialists, hospitals, home health agencies, and skilled nursing facilities are in the plan’s network?

Access to health care

  • What is the service area for the plan?
  • Do I have any coverage for care received outside the service area?
  • Who can I choose as my Primary Care Provider (PCP)?
  • Do I need a referral from my PCP to see a specialist?
  • Does my doctor need to get approval from the plan to admit me to a hospital?

Costs

  • What costs should I expect for my coverage (premiums, deductibles, copayments)?
  • What is the annual maximum out-of-pocket cost?
    • Note: PPOs have different out-of-pocket limits for in-network and out-of-network care. If you’re considering a PPO, find out what the different out-of-pocket limits are for in-network vs. out-of-network care.
  • How much will I have to pay out of pocket before coverage starts. Is there a deductible?
  • How much is my copay for services I regularly receive, such as annual physical, routine eye exams or specialist visits?
  • How much will I pay if I visit an out-of-network provider or facility?
  • Are there higher copays for certain types of care, such as hospital stays or home health care?

Extra Benefits

  • Does the plan cover any additional services that Original Medicare does not?
    • Dental costs?
    • Vision?
    • Hearing aids?
    • Acupuncture or Therapeutic Massage?
  • Are there any rules or restrictions I should be aware of when accessing these benefits?

Prescription drugs

  • Does the plan cover outpatient prescription drugs?
  • Are my prescriptions on the plan’s formulary? (https://www.medicare.gov/plan-compare)
  • Does the plan impose any coverage restrictions?
  • What costs should I expect to pay for my drug coverage (premiums, deductibles, copayments)?
  • How much will I have to pay for brand-name & generic drugs?
  • What will I pay for my drugs during the coverage gap?
  • Will I be able to use my pharmacy? Can I get my drugs through mail order?
  • Will the plan cover my prescriptions when I travel?
Do you have more questions?

Call 207-370-0143 to speak to a local agent or use the form below to send an e-mail.

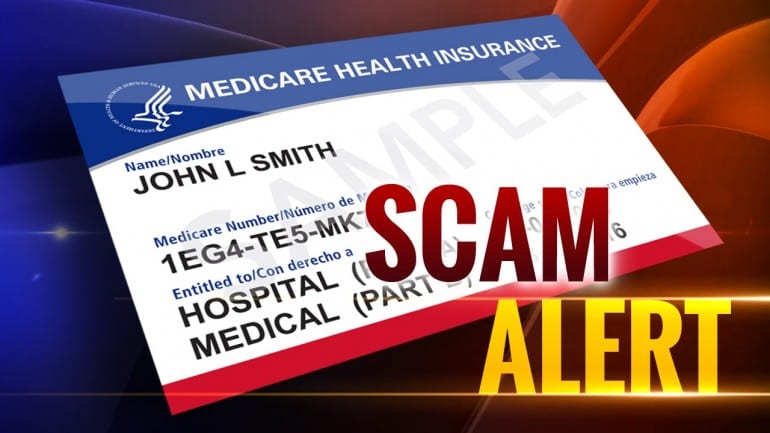
BEWARE OF CALLERS!

IMPORTANT NOTE: Social Security and Medicare do not make phone calls. If either entity needs information from you they will send a letter. They only communicate via the US Postal Service.

“If anyone calls you and asks you for information such as your social security number or Medicare ID number – HANG UP!”

I have been getting a lot of calls recently from clients saying they have been called by someone pretending to work for Social Security or Medicare. They start the conversation innocently enough but then they ask for your Medicare ID number or Social Security number or bank information. If this happens to you – HANG UP!

Social Security and Medicare already have this information. They would never need to ask you for it.

  • Hang up. If someone calls claiming to be from Medicare, asking for your Social Security number or bank information to get your new card or new benefits, that’s a scam.
  • Don’t give personal information to a caller claiming to be from Medicare. You can’t trust caller id. These calls can be spoofed so they look like they’re coming from Medicare even when they’re not. Before you give any personal information, initiate your own call to Medicare at 1-800-MEDICARE.
  • Report the call. Report Medicare imposters at 1-800-MEDICARE or ftc.gov/complaint. The more they hear from you, the more they can help fight scams.

The video below will help you recognize the scammers who ask for your Medicare number so you can get a back or neck brace or who say they need your information or money so you can get a new Medicare card. And you’ll hear from an FTC expert about how to avoid these scams:

The FTC worked with AARP to create a series of videos about imposter scams – including Medicare scams, IRS imposters and robocalls. While the videos are aimed at older Asian Americans and Pacific Islanders, the tips apply to everyone. Watch the video below about how you can protect yourself from Medicare scams: 

For more information about stopping imposter scams, visit ftc.gov/imposters. And to learn about how to stop unwanted calls, including using call blocking technology, go to ftc.gov/calls.

Have more Questions? I can help!

If you would like help finding answers to your questions, you can call me directly at 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message. I am always happy to help!

The best part about working with me is that it costs you nothing! I am paid by the insurance companies in the form of a commission when I enroll someone in a plan. This is the same way it works when you buy car insurance or your home owners insurance. You do not pay anything to the agent and you will pay the same price for your insurance that everyone pays whether they had my help or not.

“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”

Book an appointment with Maine Medicare Options using SetMore

Over-the-Counter benefits

If you have a Medicare Advantage plan then you probably have an Over-The-Counter (OTC) benefit.

receive a quarterly amount to purchase from over 150 CVS brand, over-the-counter products, including:

What is it? And How to use it?

Many of this year’s Medicare advantage plans have an OTC benefit.  This benefit provides each member a monthly fixed amount of money to use to order common over-the-counter items available to order through a catalog or at your local pharmacy. 

If your plan has this benefit you will receive a monthly, quarterly or annual amount to purchase over-the-counter products, including things like:

  • Smoking Cessation: Nicotine replacement patches
  • Oral Health: Toothpaste, toothbrushes, floss
  • Pain Relief: Ibuprofen, acetaminophen
  • Allergy: Allergy relief tablets
  • Cold Remedies: Cough drops, daytime/nighttime cold medicine
  • Digestive Health: Heartburn relief tablets, daily fiber
  • First Aid: Bandages
  • Incontinence: Bladder control products

The monthly benefit with most plans does not roll over month to month.  In other words, it is a use it or lose it system so make sure you understand how your benefit works.

If you’d like to learn more about what your plan offers or need a copy of the catalog for ordering, use the form below and we’ll call you or you can call us at 207-370-0143.

Switching To Medigap

How to switch to a Medigap plan if you have Medicare Advantage.

Switching to Medigap (Plan G) from Medicare Advantage requires some planning. There are several important things you should know.

Even if you haven’t thought about changing plans before now, understanding your rights and your options is important. Here I’ll discuss when, how and why to consider changing plans.

When can you dis-enroll from a medicare advantage plan?

There are two times each year you are allowed to disenroll from your Medicare Advantage plan.

  • The Annual Open Enrollment Period (AEP)
  • The Medicare Advantage Open Enrollment Period (MA-OEP)

The Annual Open Enrollment Period (AEP) takes place each year in the fall from October 15 through December 7.

The Medicare Advantage Open Enrollment Period (MA-OEP) is something new that was created when Congress passed the Bipartisan Balanced Budget Act in 2018. It is one last chance to change your policy for the year if you missed the Annual Open Enrollment or made a mistake during Open Enrollment. It takes place from January 1 through March 31 each year.

There are also other enrollment periods available, such as your Initial Enrollment Period (IEP) when you turn 65 and Special Enrollment Periods (SEP) that you may qualify for when you move outside the plans service area or when you retire and lose your employer group health insurance plan or qualify for another reason. [READ MORE ABOUT ENROLLMENT PERIODS]

If your goal is changing from a Advantage plan to Medigap, you need to apply as early as possible during your enrollment period. You want to be sure the Medigap plan accepts your application before you cancel your Advantage plan.

“The most important thing I tell all my clients is to never cancel a policy before they have confirmation from the new plan. It’s best to wait until you have a confirmation letter or insurance card from the new company in your hands before cancelling your old plan.”

Todd Reagin, Local Agent in Maine

Some Medigap Plans can deny you if you have a pre-existing medial conditions.

If you miss the Medigap open enrollment period, some companies can deny you coverage or charge more because of preexisting conditions. But, sometimes, you qualify for a special enrollment period that grants guaranteed issue rights.

These rights vary from state to state. To learn about what rights you have, you should talk to a licensed insurance agent who specializes in Medicare plans and is certified to help people understand all the rules and regulations of Medicare.

Would you like my help?

I am licensed by the state so I know what consumer protection laws exist to protect my clients. I am also certified to help people with Medicare Part C and D plans each year which guarantees my knowledge of Medicare regulations is current.

The best part about working with me is that it will not cost you anything to talk with me to discuss your options and review the plans that are available.  

I am paid by the insurance companies in the form of a commission when you enroll in a plan.  You will not pay anything to meet with me and you will pay the same price for your insurance that everyone pays whether they had my help or not.

“My goal is to help people and I have found great joy in being able to offer my services to people who need my help.”

Transportation & Medicare

Maine medicare covers transportation card rides doctors pharmacy low income help

Does Medicare cover transportation?

  1. Medicare Part A and B may cover emergency transportation.
  2. Medicare Part B may cover medically necessary transportation ordered by a doctor.
  3. Medicare Part A and Part B do not cover non-emergency transportation to and from your doctor’s office.
  4. Some Medicare Advantage plans may cover trips to your doctor’s office.
  5. Some Medicare Advantage plans also cover rides to and from your doctor’s office or fitness center.

Although Original Medicare (Medicare Part A and Part B) does not cover transportation to and from your doctor’s office, many Medicare Advantage plans (Medicare Part C) can cover non-emergency transportation.

In fact, some Medicare Advantage plans partner with ride-sharing services to provide transportation to members.

Some Medicare Advantage plans may cover non-emergency transportation.

Medicare Advantage plans provide the same benefits as Medicare Part A and Part B combined into one simple plan.

Many Medicare Advantage plans may also offer additional benefits such as coverage for prescription drugs, and some plans may also cover things like dental and vision.

In April 2018, the Centers for Medicare & Medicaid Services (CMS) announced plans to expand the list of benefits private insurance companies are allowed to cover as part of a Medicare Advantage plan.

The new expanded Medicare Advantage benefits can include things like:

  • Transportation to doctor’s offices
  • Wheelchair ramps
  • Handrails installed in the home
  • More coverage for home health aides
  • Air conditioners for people with asthma

These extra benefits are offered as part of an aim to focus on more preventive health and aging-in-place benefits.

Original Medicare and non-Emergency ambulance transportation.

Medicare Part B only covers non-emergency ambulance services to the nearest medical facility that is able to provide you with appropriate care if you have a written order from your doctor saying that it is medically necessary.

If you go to a facility that is farther away, Medicare’s coverage will be based on the charge to the closest facility, and you must pay the difference.

If the ambulance company thinks that Medicare might not cover your non-emergency ambulance service, they should provide you with an Advance Beneficiary Notice of Noncoverage.

Original Medicare and emergency ambulance transportation.

Medicare covers emergency ambulance transportation if you’ve had a sudden medical emergency and your health is in danger.

Medicare may pay for emergency ambulance transportation by helicopter or airplane if your condition requires rapid transportation that cannot be provided on the ground.

Coverage for emergency ambulance transportation depends on the seriousness of your condition.

In some cases, Medicare may cover transportation in an ambulance if you have End-Stage Renal Disease (ESRD) and need ambulance transportation to and from the facility where you receive dialysis treatment.

Medicare transportation costs.

If your ambulance service is covered by Medicare, Medicare Part B typically covers 80 percent of the Medicare-approved amount, and you pay 20 percent (once your deductible is met).

In 2020, the Medicare Part B deductible is $198 per year.

Do Medicare Supplement plans cover transportation?

Medicare Supplement Insurance plans (also called Medigap) are sold by private insurance companies to work alongside your Original Medicare coverage. 

A Medigap plan won’t typically cover transportation, but a Medigap plan can help cover the out-of-pocket Medicare costs that you may face if Medicare covers your transportation.

For example, if your ambulance ride to the hospital is covered by Medicare Part B, some types of Medicare Supplement plans will cover your Part B deductible, and all Medigap plans provide at least some coverage for your Part B coinsurance costs.

Medicare Supplement plans and Medicare Advantage plans are very different things, and you cannot have a Medigap plan and a Medicare Advantage plan at the same time.

Get more from your Medicare coverage.

To learn more about your Medicare Advantage plan options and to compare plans that cover transportation that may be available where you live, call and speak with a local licensed insurance agent today.

Call 207-370-0143 or toll free 866-976-9038.

Learn more about Medicare Advantage plans

Have a quick question? Send an email.


More Topics…

Does Medicare Cover Acupuncture or Chiropractic?

Medicare Advantage Vs. Original Medicare & Medigap

What are Premium Buy-Back plans?

Veterans’ Benefits and Medicare

Qualified Medical Expenses

Qualified Medical Expenses for Health Savings Account (HSA) health insurance plans and Medicare Savings Account (MSA) Medicare Advantage plans.

The following is a summary of common expenses claimed against Health Savings Accounts (HSAs) & Medicare Savings Accounts (MSAs). Due to frequent updates to the regulations governing these accounts and arrangements, this list does not guarantee reimbursement and is to be utilized as a guide for the submission of claims. For more information on IRS-qualified medical expenses, go to IRS.gov/Pub502.

Important Update: CARES Act expands use of health accounts

The new CARES Act expands eligible expenses for HSAs, FSAs, and HRAs:

  • Feminine hygiene products are now qualifying medical expenses.
  • You can now use your HSA or MSA for over-the-counter (OTC) medications without a prescription. See the Common Over-the-Counter (OTC) Medications section below for examples.
    • Many products being discussed in the news, such as lodging, disposable masks, and hand sanitizer, are considered qualifying medical expenses only with a prescription (Rx) or letter of medical necessity (LMN) from a doctor.
    • These changes will likely take effect gradually. Not all retailers will update at the same time, which may result in inconsistent shopping experiences. Such issues are likely to be resolved soon. For information on reimbursing yourself for out-of-pocket medical expenses from your HSA or MSA contact your plan.
  • You can now use your HSA or MSA for telehealth services before reaching your deductible. You can use your HSA or MSA for telehealth for qualified expenses. Both instances are effective until Dec. 31, 2021.

Common IRS-Qualified Medical Expenses

  • Acupuncture
  • Ambulance
  • Artificial limbs
  • Artificial teeth*
  • Birth control treatment
  • Blood sugar test kits for diabetics
  • Breast pumps and lactation supplies
  • Chiropractor
  • Contact lenses and solutions*
  • Crutches
  • Dental treatments (including X-rays, cleanings, fillings, sealants, braces and tooth removals*)
  • Doctor’s office visits and co-pays
  • Drug addiction treatment
  • Drug prescriptions
  • Eyeglasses (Rx and reading)*
  • Fluoride treatments*
  • Feminine hygiene products
  • Fertility enhancement (including in-vitro fertilization)
  • Flu shots
  • Guide dogs
  • Hearing aids and batteries
  • Infertility treatment
  • Inpatient alcoholism treatment
  • Insulin
  • Laboratory fees
  • Laser eye surgery*
  • Medical alert bracelet
  • Medical records charges
  • Midwife
  • Occlusal guards to prevent teeth grinding
  • Orthodontics*
  • Orthotic Inserts (custom or off the shelf)
  • Over-the-counter medicines and drugs (see more information below)
  • Physical therapy
  • Special education services for learning disabilities (recommended by a doctor)
  • Speech therapy
  • Stop-smoking programs (including nicotine gum or patches, if prescribed)
  • Surgery, excluding cosmetic surgery
  • Vaccines
  • Vasectomy
  • Vision exam*
  • Walker, cane
  • Wheelchair

Important Note: If you have a Medicare MSA plan, some services, like dental care, routine vision care, and Part D drugs, are Qualified Medical Expenses, but are NOT covered by Medicare Part A or Part B. If you use the money in your account for this type of expense, the money will not be taxed. However, these expenses won’t count toward your plan deductible.

Common Over-the-Counter (OTC) Medicines

Examples include, but are not limited to:

  • Acid controllers
  • Acne medicine
  • Aids for indigestion
  • Allergy and sinus medicine
  • Anti-diarrheal medicine
  • Baby rash ointment
  • Cold and flu medicine
  • Eye drops*
  • Feminine antifungal or anti-itch products
  • Hemorrhoid treatment
  • Laxatives or stool softeners
  • Lice treatments
  • Motion sickness medicines
  • Nasal sprays or drops
  • Ointments for cuts, burns or rashes
  • Pain relievers, such as aspirin or ibuprofen
  • Sleep aids
  • Stomach remedies

Services That May Be Eligible with a Letter of Medical Necessity Completed

This list is not all-inclusive:

  • Weight-loss program only if it is a treatment for a specific disease diagnosed by a physician (e.g., obesity, hypertension, heart disease)
  • Compression hosiery/socks, antiembolism socks or hose
  • Massage treatment for specific ailment or diagnosis
  • CPR classes for adult or child
  • Improvements or special equipment added to a home or other capital expenditures for a physically handicapped person

Ineligible Expenses

Listed below are some services and expenses that are not eligible for reimbursement. This list is not all-inclusive:

  • Aromatherapy
  • Baby oil
  • Baby wipes
  • Breast enhancement
  • Cosmetics and skin care
  • Cotton swabs
  • Dental floss
  • Deodorants
  • Hair re-growth supplies and/or services
  • Health club membership dues
  • Humidifier
  • Lotion
  • Low-calorie foods
  • Mouthwash
  • Petroleum jelly
  • Shampoo and conditioner
  • Spa salts

Eligible Dependent Care Expenses

  • Au pair services
  • Babysitting services
  • Before- and after-school programs
  • Custodial or eldercare expenses, in-home or daycare center (not medical care)
  • Nursery school
  • Pre-kindergarten
  • Summer day camp (not educational in nature)

Ineligible Dependent Care Expenses

  • Clothing
  • Food/meals
  • Kindergarten and higher education/tuition expenses
  • Overnight camp

This list is not comprehensive. It is provided to you with the understanding that HSA Bank is not engaged in rendering tax advice. The information provided is not intended to be used to avoid federal tax penalties. For more detailed information, please click here. If tax advice is required, you should seek the services of a professional.

*Some restrictions apply or prior qualifications must be met. Please contact your plan or a tax specialist for more information.

Coronavirus & Medicare

24 Hour Nurse Help Lines

  • Aetna – 1-800-556-1555
  • AARP United Healthcare 1-877-365-7949
  • Anthem Maine Health – 1-800-700-9184
  • Harvard Pilgrim Stride – 1-888-333-4742
  • Humana – 1-800-622-9529
  • Martins Point Generations Advantage – 1-800-530-1021
  • MEA Benefits Trust – 1-800-607-3262
  • Medi-Share MDLive – 1-888-964-3387
  • Wellcare of Maine – 1-800-581-9952

Medicare will cover coronavirus tests & doctor visits.

Here’s how to get one if you think you have symptoms

Call your doctor. Lab services are covered by Original Medicare and Medicare Advantage plans, but if you want a random test out of the blue, it would not be covered if there’s no medically necessary reason for it. If you suspect you may have been exposed to the COVID-19 virus, call your doctor and in the current environment, if your doctor is concerned, they will say the test is medically necessary. If your doctor bills you for an office visit, that office visit will also be covered.

Let’s discuss the various ways that Medicare will cover the testing and medical care for the two different types of Medicare plans.

Original Medicare and Medicare Advantage plans:

If you have a Medicare Advantage Plan (Part C) in Maine.

Most Medicare Advantage plans in Maine have announced they will waive co-pays for all diagnostic testing related to COVID-19, That includes all member costs associated with diagnostic testing.

Some plans are also offering zero co-pay telemedicine visits for any reason as well as expanding several programs to help people address associated anxiety and stress.

If you have a Original Medicare & a Supplement (Medigap).

Medicare Part B (Medical Insurance) covers a test to see if you have coronavirus (officially called 2019-novel coronavirus or COVID-19). This test is covered when your doctor or other health care provider orders it. You usually pay nothing for Medicare-covered clinical diagnostic laboratory tests.

IMPORTANT NOTE:
Your doctor will need to wait until after April 1, 2020 to be able to submit a claim to Medicare for this test.

Mother always said, “An ounce of prevention is worth a pound of cure.” And she was right!

While the average risk of contracting COVID-19 remains low in the U.S., top experts now warn people in high-risk groups to be cautious – especially if they are elderly and have an underlying medical condition.

“Avoid large crowds, no long trips and above all, don’t get on a cruise ship,” Dr. Anthony Fauci, director of the National Institute of Allergy and Infectious Diseases, said in an interview on NBC’s “Meet the Press.”

The Centers for Disease Control and Prevention recommends that high-risk individuals stock up on supplies (such as extra medications and groceries), keep space between yourself and others, wash your hands often and avoid crowds. And, if there is an outbreak in your community, remain at home as much as possible.

Symptoms of COVID-19 include fever, cough, shortness of breath and difficulty breathing. Severe cases can lead to pneumonia, severe acute respiratory syndrome, kidney failure and death, according to the World Health Organization.

If you develop any symptoms that are concerning, you should contact your primary-care provider — by phone — for guidance. The CDC has encouraged providers to use their best judgment for who should be tested, which may be based on your symptoms or other factors such as known exposure to an infected person.

If your doctor or other provider thinks you need testing, they’ll contact their local health department or the CDC for instructions on where you can get the test, according to the National Institutes of Health.

The test may involve a swab, blood draw or other method, depending on where the test is administered.

If you have further questions about how your plan will cover testing or treatments call 1-800-Medicare or call the phone number for Member Services on the back of your insurance card.

Still have questions?

Just fill out the form below and we’ll research your question and email or call you back with the answer.

Home Health Services

Does Medicare Cover Home Health Care?

Home health care services are a valuable Medicare benefit that provides skilled nursing care, therapy and other aid to people who are largely or entirely confined to their homes.

To be covered, the services must be ordered by a doctor, and a home health agency that Medicare has certified must provide the care.

Medicare (Part A and/or Part B) typically covers the following home health services:

  • Part-time or “intermittent” skilled nursing care such as changing wound dressings, feeding through a tube and injecting medicine, provided on a part-time or intermittent basis. Your combined home nursing and personal care cannot exceed eight hours a day or 28 hours a week, except in limited circumstances. If you need full-time or long-term nursing care, you probably will not qualify for home health benefits.
  • Home health aides to assist with personal activities such as bathing, dressing or going to the bathroom if such help is necessary because of your illness or injury. Medicare covers these services only if you also are getting skilled nursing or therapy.
  • Occupational, physical and speech therapy with professional therapists to restore or improve your ability to perform everyday tasks, speak or walk in the aftermath of an illness or injury or to help keep your condition from getting worse.
  • Medical social services such as counseling for social or emotional concerns related to your illness or injury if you’re receiving skilled care and help finding community resources if you need them.
  • Medical supplies such as catheters and wound dressings related to your condition when your home health agency provides them. This might also include durable medical equipment from the home health agency, such as walkers or wheelchairs, but for those Medicare does not pay the full cost. You usually are responsible for 20 percent of the Medicare-approved amount.
  • Osteoporosis drugs for women that are injected – Medicare helps pay for an injectable drug for osteoporosis and visits by a home health nurse to inject the drug if you meet these conditions

Generally, your home health care agency coordinates the services the doctor orders for you.

Medicare does not pay for:

  • 24-hour-a-day care at home
  • Meals delivered to your home
  • Homemaker services (like shopping, cleaning, and laundry), when this is the only care you need
  • Custodial or personal care (like bathing, dressing, or using the bathroom), when this is the only care you need

Note: If you have a Medicare Advantage plan, your plan may cover some services not covered by original Medicare. Check with your insurance agent to ask what home healthcare benefits may be covered by your plan.

Who is eligible?

To be eligible for Medicare home health benefits, you must meet all of these conditions: 

  • You are home bound. That means you are unable to leave home without considerable effort or without the aid of another person or a device such as a wheelchair or a walker.
  • You have been certified by a doctor, or by a medical professional who works directly with a doctor (such as a nurse practitioner), as being in need of intermittent occupational therapy, physical therapy, skilled nursing care and/or speech-language therapy.
  • That certification arises from a documented, face-to-face encounter with the medical professional no more than 90 days before or 30 days after the start of home health care.
  • You are under a plan of care that a doctor established and reviews regularly. The plan should include what services you need and how often, who will provide them, what supplies are required and what results the doctor expects.
  • Medicare has approved the home health agency caring for you.

You’re not eligible for the home health benefit if you need more than part-time or “intermittent” skilled nursing care. You may leave home for medical treatment or short, infrequent absences for non-medical reasons, like attending religious services. You can still get home health care if you attend adult day care.

Your costs with Original Medicare

Before you start getting your home health care, the home health agency should tell you how much Medicare will pay. The agency should also tell you if any items or services they give you aren’t covered by Medicare, and how much you’ll have to pay for them.

This should be explained by both talking with you and in writing. The home health agency should give you a notice called the Advance Beneficiary Notice before giving you services and supplies that Medicare doesn’t cover.

Medicare’s website has a search and comparison tool to help you find certified home health agencies in your area. If you have original Medicare, Parts A and B, you can choose any approved agency.

Medicare Advantage (Part C)

If you have a Medicare Advantage plan from a private insurance company, you may have to use an agency that is in the plan’s network.

Before you start receiving care, the agency should let you know, verbally and in writing, whether some of the services they provide are not covered by Medicare and what you would pay for them.

Have more questions?

Use the form below to ask for more information.


COVID-19 Enrollment Period

COVID-19 Special enrollment period available to those affected by the pandemic.

On March 13, 2020, President Trump declared a nationwide emergency pursuant to Sec. 501(b) of Stafford Act to avoid governors needing to request individual emergency declarations.

The Centers for Medicare & Medicaid Services (CMS) on May 5th issued a memorandum that clarifies the exceptional conditions that qualify for a special enrollment period (SEP) for individuals affected by a FEMA declared weather related emergency or major disaster.

The agency said that the Special Enrollment Period (SEP) is applicable and available for beneficiaries who were eligible for, but unable to make, an election because they were affected by the ongoing public health crisis.

This SEP is available nationwide to residents of all states, tribes, territories, and the District of Columbia as of March 1 if you were unable to and did not make an election during another valid election period as a result of the emergency. This includes enrollment and disenrollment elections.

How do you know if you qualify?

CMS considers individuals as “affected” and eligible for this SEP under FEMA if you:

  • Reside, or resided at the start of the incident period, in an area for which FEMA has declared an emergency or a major disaster and has designated affected counties as being eligible to apply for individual or public level assistance;
  • Had another valid election period at the time of the incident period; and
  • Did not make an election during that other valid election period.
  • Mulcahy also said the SEP is available to individuals who do not live in the affected areas but rely on help to make health care decisions from friends or family members who live in the affected areas.

The SEP is available from the start of the incident period and for four full calendar months after the start of the incident period from March 1 to June 30, 2020.

You will receive one opportunity to make that missed election because of this SEP.

Further, you do not have to provide proof that you were affected by the pandemic-related emergency.

If your insurance representative is unaware of this SEP, they should refer to the following sections in posted manual guidance for details on the SEP:

  • Section 30.4.4.18 of Chapter 2 (Medicare Advantage Enrollment and Dis-enrollment) of the Medicare Managed Care Manual.
  • Section 30.3.8.17 of Chapter 3 (Eligibility, Enrollment and Dis-enrollment) of the Medicare Prescription Drug Benefit Manual.

Frequently asked questions and answers for this SEP are available at the following links on the CMS website. These will address issues such as eligibility for the SEP and how to enroll:

Questions and Answers on the Medicare Managed Care Eligibility and Enrollment webpage.
Questions and Answers on the Medicare Prescription Drug Eligibility and Enrollment webpage.

Need help enrolling or have more questions?

Use the form below to get help.


Less than 20 employees?

If you work for a small company (under 20 employees), you MUST enroll in Medicare at 65.

You need to sign up before turning 65

If you work for a small employer (less than 20 employees) then you will need to sign up for both Parts A & B before you turn 65. This is because Medicare becomes the primary payer of your health costs and your health insurance is no longer responsible for the portion of the bill that would be covered by Medicare.

Different Rules for Small Companies

The laws that prohibit large insurers from requiring (or even persuading) Medicare-eligible employees to drop the employer plan and sign up for Medicare do not apply to companies and organizations that employ fewer than 20 people.

Medicare Pays First

When you turn 65 Medicare automatically becomes primary and the employer plan provides secondary coverage. In other words, Medicare settles your medical bills first, and the employer plan only covers services that it covers but Medicare doesn’t. Therefore, if you fail to sign up for Medicare when required, you will essentially be left with no coverage.

It’s therefore extremely important to sign up for Medicare before you turn 65 because if you do not sign up during your initial enrollment period you will have to wait until January to enroll and your Medicare benefit will not begin until July 1st, leaving you at risk.

NOTE: Signing up for Medicare Part B when you also have employer insurance will not jeopardize your chances of buying supplemental insurance after your employment ends. When Medicare is primary to the employer plan, you have the right to buy supplemental insurance with full federal protections if you do so within 63 days of the employer coverage ending.

Occasionally some insurance companies may offer to cover claims even if you don’t have Part B. Don’t risk it. The insurance company could change that decision at any time without warning, and leaving you stuck with all the expenses that Part B would normally cover. It’s not worth the risk.

“I always advise my clients to enroll in Parts A & B if the employer has fewer than 20 employees. It’s better to be safe then sorry.”

Todd Reagin, Insurance Broker

One Exception

The ONLY exception to this rule is for employers who participate in a “multi employer plan.”  In this case if one of the employers has more than 20 employees then all the employers in the group are entitled to an exemption and employees can postpone their Part B coverage. You can read more about that exception here: https://www.cms.gov/Medicare/Coordination-of-Benefits-and-Recovery/EmployerServices/Small-Employer-Exception

Would you like my help?

If you would like to talk to me or schedule a meeting at your home or my office, you can reach me at 207-370-0143 or use my simple form on the CONTACT page of this site to send an email message.

The best part about working with me is that it will not cost you anything to meet with me to discuss your options or to review the plans that are available.  I am paid by the insurance companies in the form of a commission if you enroll in a plan.

You will not pay any more than anyone else and you are under no obligation whatsoever to enroll in any plans if you meet with me.  My goal is to help you and I have found great joy in being able to offer my services to people who need my help.

If you are turning 65 this year or retiring, you may have questions.

Call me today and I will be happy to explain all your options and help you compare plans so you can choose the coverage you need for a price you can afford.

Schedule a phone call or an in-person meeting.

I can answer all your questions over the phone or we can meet face-to-face and I can help you with everything you need to know. I have all the forms and applications you need and I can also help you complete them.

1 2 3 4 5